04 / EASE SOLUTIONS

Documentation & Tax Defensibility

Do the contract, product, participant function, route, payment and performance form a coherent economic explanation?
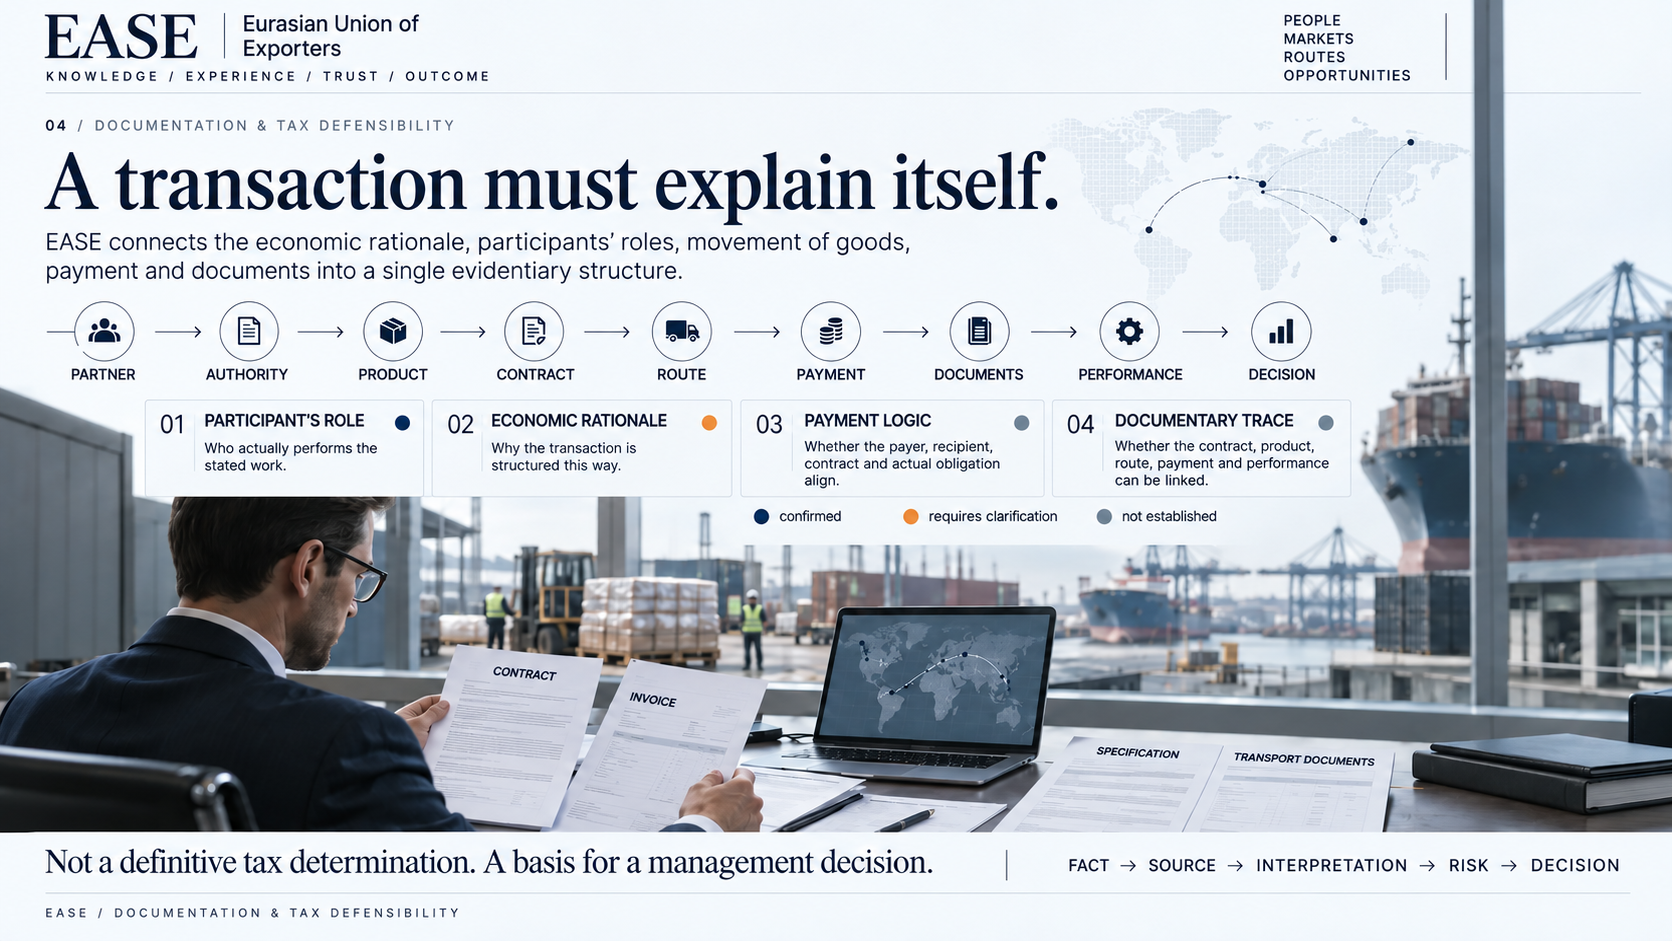
Documentation & Tax Defensibility for an international transaction: contract, documents, route, payment and actual performance

A transaction must explain itself through its documents, economic rationale and connection to actual performance.

EASE does not issue definitive tax determinations.
EASE shows whether a decision can withstand scrutiny against the facts.

Tax evidentiary readiness is neither a promise of the outcome of an audit nor a substitute for a tax adviser. It is a reproducible record of what has been established, the grounds on which it rests, which interpretations are possible, what remains not established and which action is permissible on the basis of the current version of the materials.

DISCIPLINE OF CONCLUSIONS

One fact. Several interpretations. One responsible decision.

A commercial document does not by itself explain the economic rationale of a transaction. EASE separates an observable circumstance from its significance for the specific transaction.

01 / FACT

What is actually observable

A document, register entry, payment, route, participant action or confirmed change.

02 / INTERPRETATION

What it may mean

The primary and alternative explanations, without presenting an assumption as an established circumstance.

03 / DISTINGUISHING FACTOR

What will determine which explanation applies

A missing document, explanation, source, link to the commitment or verification of actual performance.

04 / DECISION

What may be done now

Proceed, proceed subject to conditions, stop or return the matter for re-verification.

TAX EVIDENTIARY MATRIX

A transaction must explain itself before others begin explaining it for you.

Partner’s functionWho actually performs the work for which the remuneration is paid?Confirm the function, resources and actual performance.
Payment rationaleWhy is payment made by this particular party, through this route and in this sequence?Link the payer, commitment, invoice and authority.
Document integrityAre the contract, product, price, route, payment and outcome of performance consistent?Record discrepancies, their significance and the conditions for correction.
Arm’s-length basis and rationaleDoes the arrangement have a business rationale beyond a formal set of documents?Separate what has been established from an explanation that still requires confirmation.
OUTCOME FOR THE DECISION-MAKER

Materials for management decision-making.

Not a folder of documents, but a coherent economic explanation of the transaction and its limits.

  • evidence register with sources and dates;
  • matrix of documentary gaps;
  • map linking facts, documents and performance;
  • analytical memorandum for management decision-making;
  • open questions and conditions for re-verification.

EASE does not determine tax obligations on behalf of a government authority, issue an opinion guaranteeing a particular position or substitute for licensed or specialist expertise where such expertise is required.

Discuss the assignment
Architectural illustration of Moscow near Starovagankovsky Lane and Vozdvizhenka Street
01 / MOSCOW

Starovagankovsky Lane · Vozdvizhenka Street
Architectural illustration of St Petersburg near Bolshaya Morskaya Street
02 / ST PETERSBURG

3 Bolshaya Morskaya Street